Understanding how emerging technology and innovation shape the economy
The Federal Reserve Bank of San Francisco established the Technology & Growth Center in 2026 to advance understanding of the economic impacts of emerging technology and innovation.
Expanding on the work begun under an earlier program, the EmergingTech Economic Research Network (EERN), the Technology & Growth Center offers policymakers, researchers, and industry and community leaders a place to discover cutting-edge insights and connect with others to explore how technology is transforming our economy.
Located in the heart of technological innovation in the U.S., the Center examines the effects of technological change on economic growth and productivity, including potential implications for monetary policymakers in the short- to medium-term.
2026 Economic Research Symposium
Hosted by the Federal Reserve Bank of San Francisco, Philip Lane, Member of the Executive Board of the European Central Bank, delivers the keynote address at the 2026 Economic Research Symposium, “AI and the Economy.”
Interested in learning more about the Technology & Growth Center? Contact Huiyu Li or Kevin Ortiz.
Subscribe to receive updates on Center research and events.
Speeches and Remarks
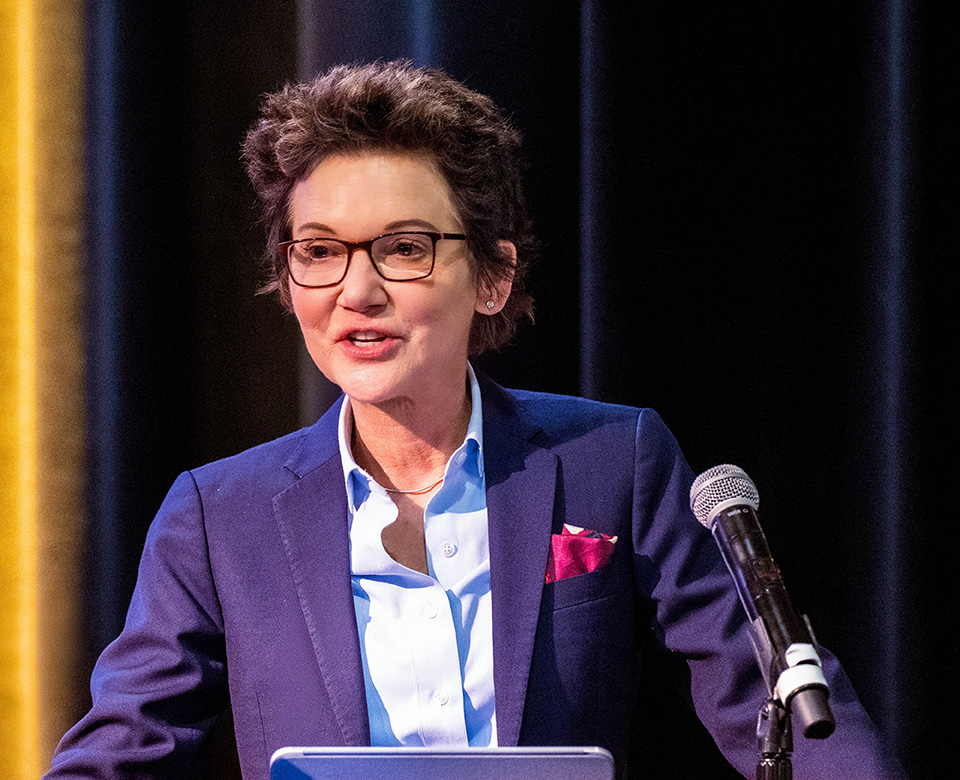
Keynote Remarks by Mary C. Daly on AI and the Economy
February 17, 2026
Hosted by the Silicon Valley Leadership Group and San Jose State University, President Daly delivered keynote remarks on AI and the U.S. economy. Following her remarks, she sat down with Bloomberg Tech’s Ed Ludlow for a moderated conversation and audience questions.
Technology & Growth Center FAQ
What is productivity?
Productivity is a measure of how much output (goods and services) is produced per unit of input (material, labor, and capital). This can be measured at the worker or business level as well as the sector, regional, or national level. It essentially indicates how efficiently inputs are being used to generate output.
Two common measures of productivity are: (1) labor productivity, which measures output per hour worked; and (2) total factor productivity, which assesses all inputs including labor, capital, raw materials, energy, etc.
Several factors can impact productivity, notably including technological advancements and their integration into existing business models, the creation of new ones, and diffusion into the broader economy.
Productivity increases are a key ingredient for economic growth.
What is economic growth?
Economic growth is the increase in the total production of goods and services in a nation, region, or sector over a specific period of time. Several factors can impact economic growth, notably including population growth, automation, and productivity boosts through emerging technologies. The most commonly used measure of economic growth for the United States is the growth rate of real gross domestic product (GDP), which measures the quantity of goods and services produced in the United States.
What is emerging technology?
Emerging technology refers to new or rapidly developing technologies that have the potential to meaningfully impact economic growth and the labor market. Recent advancements in artificial intelligence (AI) are an example that present novel capabilities with the potential to transform the economy. Some economists believe AI could be a modern general-purpose technology (GPT) like the steam engine and electricity.
What is a general-purpose technology?
According to Bresnahan and Trajtenberg (1995), general-purpose technologies (GPTs) are “engines for growth.” They are technologies that are pervasive, improve over time, and lead to complementary innovation. To transform the economy, they require both new types of physical equipment and structure and also large intangible investments and fundamental changes to the organization of production such as creating new business processes and training workers.
A GPT has the potential to profoundly change how work and daily activities are performed. It can transform how an economy and society functions. Notable historical examples include: steam engines, railroads, electricity, internal combustion engines, and information and communications technology.
Artificial intelligence (AI) has the potential to be a GPT given its capacity to change how every sector of the economy operates and how people live.